The Strategic Partner
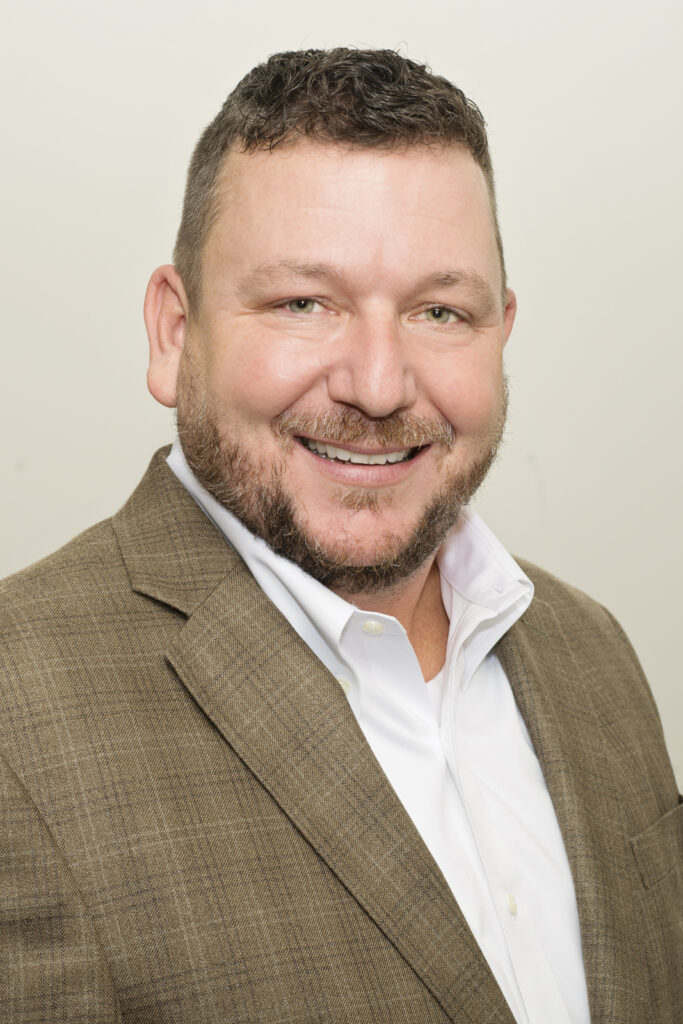
With a background as a former Vice President of Analytics and Strategy, Mike Ward brings an uncommon level of precision to the mortgage process. He does not simply process loans; he structures them with intent. By applying an analytical approach to every detail, Mike helps protect your timeline and surface potential issues early, before they turn into last-minute surprises.
Persistence is one of Mike’s defining strengths. If a transaction becomes complex, he leans into the challenge, navigating hurdles others may miss. His approach is refreshingly straightforward: clear answers, realistic expectations, and proactive communication at every milestone. Mike believes you deserve a mortgage experience that is organized, predictable, and as stress-free as possible.
The Roadmap
How We Get You Home
01
Strategy
We define your goals to select the perfect loan program for your financial future.
02
Pre-Approval
A rigorous verification of assets and income to establish true, verified buying power.
03
Execution
Proactive daily loan management ensures every document is cleared ahead of schedule.
04
Closing
The finish line. We ensure a smooth signing so you get your keys exactly on time.
The Strategy Edge
Before mortgages, I served as VP of Analytics and Strategy. I use those skills to protect your timeline and identify risks before they become surprises. Persistence is my specialty—especially when a deal gets complicated.
Consistency Earns Trust
I take a straightforward approach to lending: clear answers, honest expectations, and proactive communication at every step. You deserve a process that feels structured and predictable.
FAQs
A pre-qualification is a surface-level estimate based on unverified data. My strategic pre-approval involves a deep dive into your tax returns, credit data, and assets. By running this “stress test” upfront, we identify and clear potential underwriting hurdles before you ever make an offer, giving you the same negotiating power as a cash buyer.
It comes down to a “break-even” analysis. FHA is excellent for lower down payments and flexible credit, but it carries permanent mortgage insurance. Conventional loans often have slightly higher rates for lower credit scores but allow you to cancel your PMI once you reach 20% equity. I provide a side-by-side analytical comparison to show which option costs you less over your expected time in the home.
Yes. While many retail banks strictly require 20% down for high-balance loans, my access to specialized “Non-Conforming” channels allows for 10% or 15% down payment options for qualified borrowers. This is a strategic move for clients who prefer to keep their capital deployed in the market rather than tied up in home equity.
C2P is a “one-time close” process. We secure your lot, your builder’s contract, and your long-term mortgage all at once. You lock in your permanent interest rate before construction begins, protecting you from market spikes. During the build, you only pay interest on the funds actually disbursed to the builder, keeping your monthly carry costs low.
Consistency is the key to a smooth closing. Avoid making large, undocumented deposits into your bank accounts, do not apply for new credit (like a car or furniture), and maintain your current employment status. Even a small change in your financial profile can trigger a re-underwrite, so I recommend consulting with me before making any significant financial moves during the process.