A home loan plan you can trust. Dedicated mortgage support in Texas and Oklahoma.
Clear answers. Smart options.
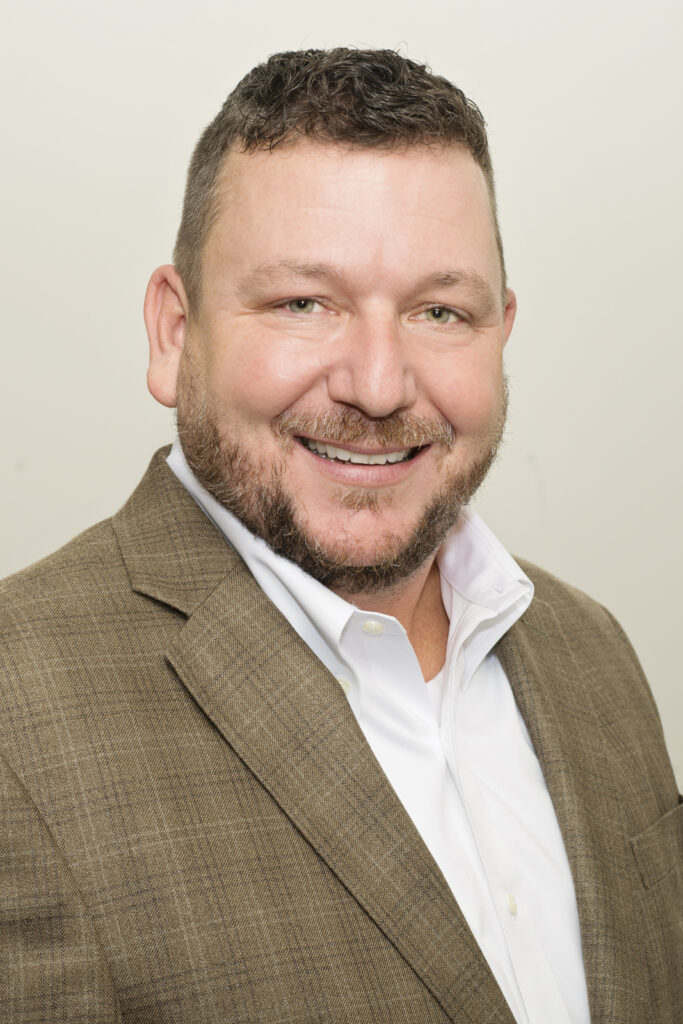
The Strategic Partner
With a background as a former VP of Analytics and Strategy, Mike Ward brings a level of precision to the mortgage process that is rare in the industry. Mike doesn’t just process loans; he engineers them. He utilizes his analytical expertise to scrutinize every detail, protecting your timeline and identifying potential risks before they ever become surprises.
Persistence is Mike’s specialty. When a deal becomes complicated, he leans into the challenge, navigating hurdles that others might overlook. His approach to lending is Refreshingly straightforward: you can expect clear answers, honest expectations, and proactive communication at every milestone. Mike believes you deserve a mortgage experience that is as structured, predictable, and stress-free as possible.
Types of Loans
Conventional Loan
Low down payment options (3%–5% for qualified buyers)
PMI can be removed when you reach enough equity
Flexible terms + strong option for high-credit borrowers (PMI)
FHA Loan
Often lower than standard market rates.
Enter the market with as little as 3.5% down
Mandatory upfront and monthly insurance.
VA Loan
0% down for eligible borrowers
No monthly mortgage insurance
Competitive rates + flexible guidelines
savings.
C2P Loan
Single application for land and build.
Secure your permanent rate before building begins.
Lower payments while your home is under construction.
Jumbo Loan
Financing for luxury properties exceeding standard limits.
Strategic paths available with as little as 10% down.
We use your full financial profile, including RSUs and investments, to qualify.
Conventional loans are offered by private lenders and typically follow Fannie Mae and Freddie Mac guidelines. With strong credit and stable income, you can often qualify for competitive pricing and flexible terms like 30-year fixed or 15-year fixed. Putting 20% down can help you avoid private mortgage insurance (PMI) and build equity faster, but many conventional programs allow a lower down payment with PMI required until you reach sufficient equity.
FHA loans are insured by the Federal Housing Administration and are designed to be more flexible for many first-time buyers. In many cases, you can purchase with as little as 3.5% down, and credit guidelines are often more forgiving than conventional financing. FHA loans include Mortgage Insurance Premium (MIP) (upfront and monthly), which helps make the program accessible with a smaller down payment. Another advantage is that FHA loans are assumable, meaning a future buyer may be able to take over your loan terms when you sell. I offer FHA financing and will help you determine whether it’s the right fit for your goals.
A VA loan is a home loan benefit earned through service and is available to eligible active-duty service members, veterans, and some surviving spouses. Eligibility is confirmed through a Certificate of Eligibility (COE) and the VA-approved application process. VA loans often allow 0% down and typically have no monthly mortgage insurance, which can meaningfully reduce the payment compared to other low-down-payment options. VA financing may also be used to purchase a home, refinance an existing VA loan, and support certain specially adapted housing needs for service-connected disabilities.
A Construction-to-Permanent mortgage is used to finance the construction of your home, lock in your interest rate and close before construction begins. Once construction has been completed, the C2P loan converts to a permanent mortgage.
A Jumbo loan is financing that exceeds the conforming loan limit, which is updated annually and can vary by county. For 2026, the baseline one-unit conforming limit in most areas is $832,750. (FHFA.gov) Jumbo loans are typically underwritten with stricter credit and asset requirements, and they may require larger down payments or reserves depending on the scenario. The benefit is flexibility: jumbo financing can help you purchase higher-priced homes while tailoring the structure to your broader financial profile.
The Roadmap
How We Get You Home
01
Strategy
We define your goals to select the perfect loan program for your financial future.
02
Pre-Approval
A rigorous verification of assets and income to establish true, verified buying power.
03
Execution
Proactive daily loan management ensures every document is cleared ahead of schedule.
04
Closing
The finish line. We ensure a smooth signing so you get your keys exactly on time.
The Strategy Edge
Before mortgages, I served as VP of Analytics and Strategy. I use those skills to protect your timeline and identify risks before they become surprises. Persistence is my specialty—especially when a deal gets complicated.
Consistency Earns Trust
I take a straightforward approach to lending: clear answers, honest expectations, and proactive communication at every step. You deserve a process that feels structured and predictable.
Strategic Insights & Mortgage Guides
Clear answers, market trends, and expert advice to help you navigate your home financing journey.
When buyers enter the market, they usually focus heavily on the down payment and monthly mortgage principal and interest. However, budgeting for a home requires looking at the total picture. From property taxes and homeowners insurance (often bundled into escrow) to unexpected maintenance reserves, preparing early protects you from last-minute financial stress.
How to Qualify for a FHA Loan Without Liquidating Your Investments
Purchasing a luxury property? Learn how lenders evaluate non-traditional assets like RSUs, stock options, and investment portfolios to help you secure a jumbo loan with as little as 10% down.

JUMBO LOAN
Traditional underwriting rules don’t always fit high-earning professionals or those with complex compensation packages. If a large portion of your wealth is tied up in equity compensation, restricted stock units (RSUs), or diversified portfolios, you don’t necessarily have to sell them off to buy a home. Strategic lenders know how to leverage your full financial profile.
Our Experts

Beyond the Down Payment
Buying a home involves more than just the purchase price and down payment. Discover the hidden expenses like escrow, HOA fees, and closing costs so you can budget with total confidence.

Down Payment
When buyers enter the market, they usually focus heavily on the down payment and monthly mortgage principal and interest. However, budgeting for a home requires looking at the total picture. From property taxes and homeowners insurance (often bundled into escrow) to unexpected maintenance reserves, preparing early protects you from last-minute financial stress.
Pre-Approval Strategy
A client reviewing financial reports alongside a laptop displaying a credit score dashboard.
Mortgage Solutions
Our broker is seen actively explaining the details of a mortgage application and key market trends, utilizing both traditional printed documents and a digital tablet for a comprehensive review. The focus is on transparency and education, ensuring the client feels confident and well-informed as they explore financing opportunities.
At Premier Mortgage Solutions, we believe that securing a mortgage is more than just a transaction; it’s the first step toward your new home. We are committed to simplifying the complex, offering tailored advice, and finding the best financial solutions to match your unique goals and budget. Whether you are a first-time buyer or looking to refinance, a professional consultation is the key to a smooth and successful experience.
Our Mission
“Empowering your future, one mortgage at a time—turning complex financial choices into clear paths to homeownership.”
At Premier Mortgage Solutions, our mission is to simplify the lending process and put your financial goals first. We believe that every client deserves transparent advice, personalized mortgage options, and a dedicated guide to help navigate the path from application to closing. Your dream home is within reach, and we are here to make financing it straightforward, stress-free, and tailored entirely to you.
Four Key Pillars of Success
Navigating the mortgage landscape can feel overwhelming, but it doesn’t have to be. At Premier Mortgage Solutions, we believe in demystifying the process by focusing on four fundamental pillars. Whether you are taking your first steps or are a seasoned investor, understanding these areas will empower you to make confident, informed decisions about your financing. Here is how we guide you through each stage of your journey.

Strategic Planning
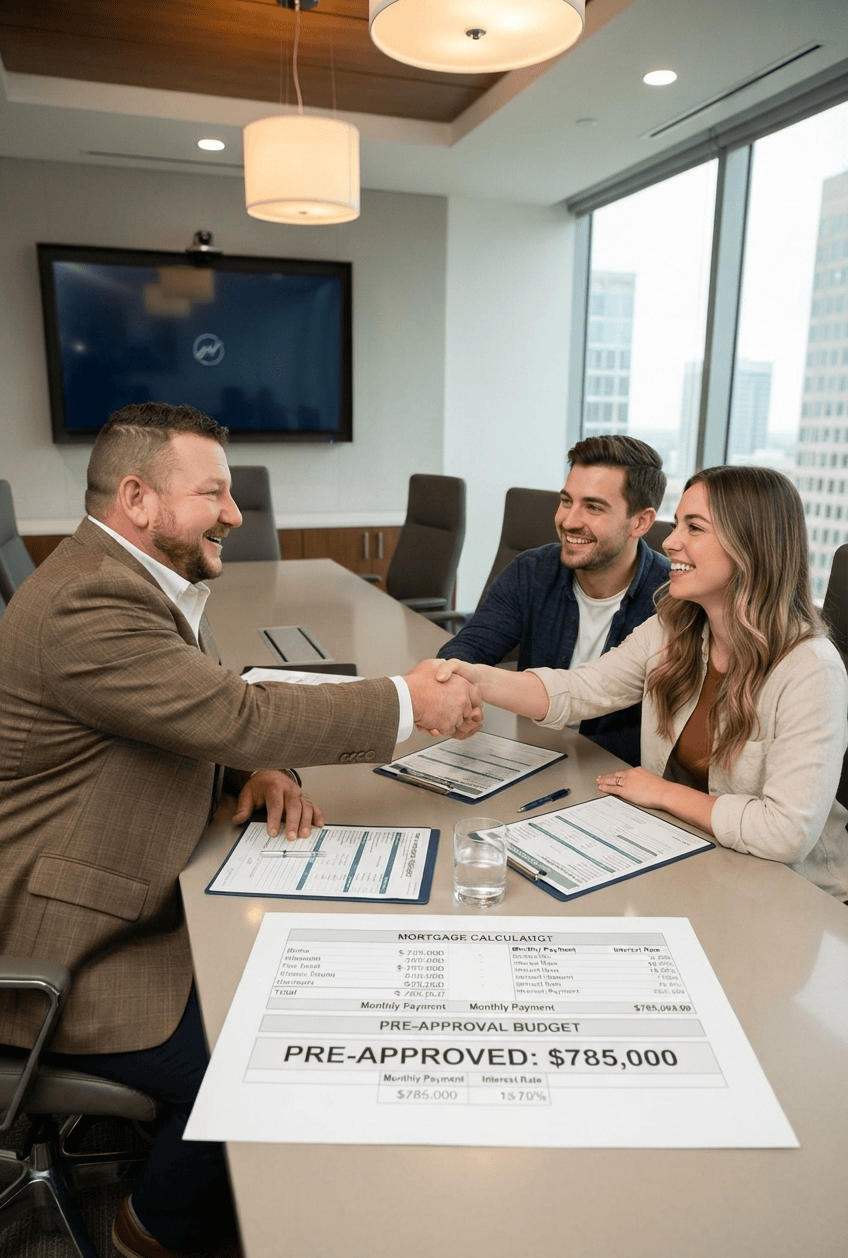
The foundation of a successful home purchase is knowing exactly what you can afford and securing a pre-approval. This step involves a detailed review of your income, assets, and credit to determine your budget.

Needs Analysis
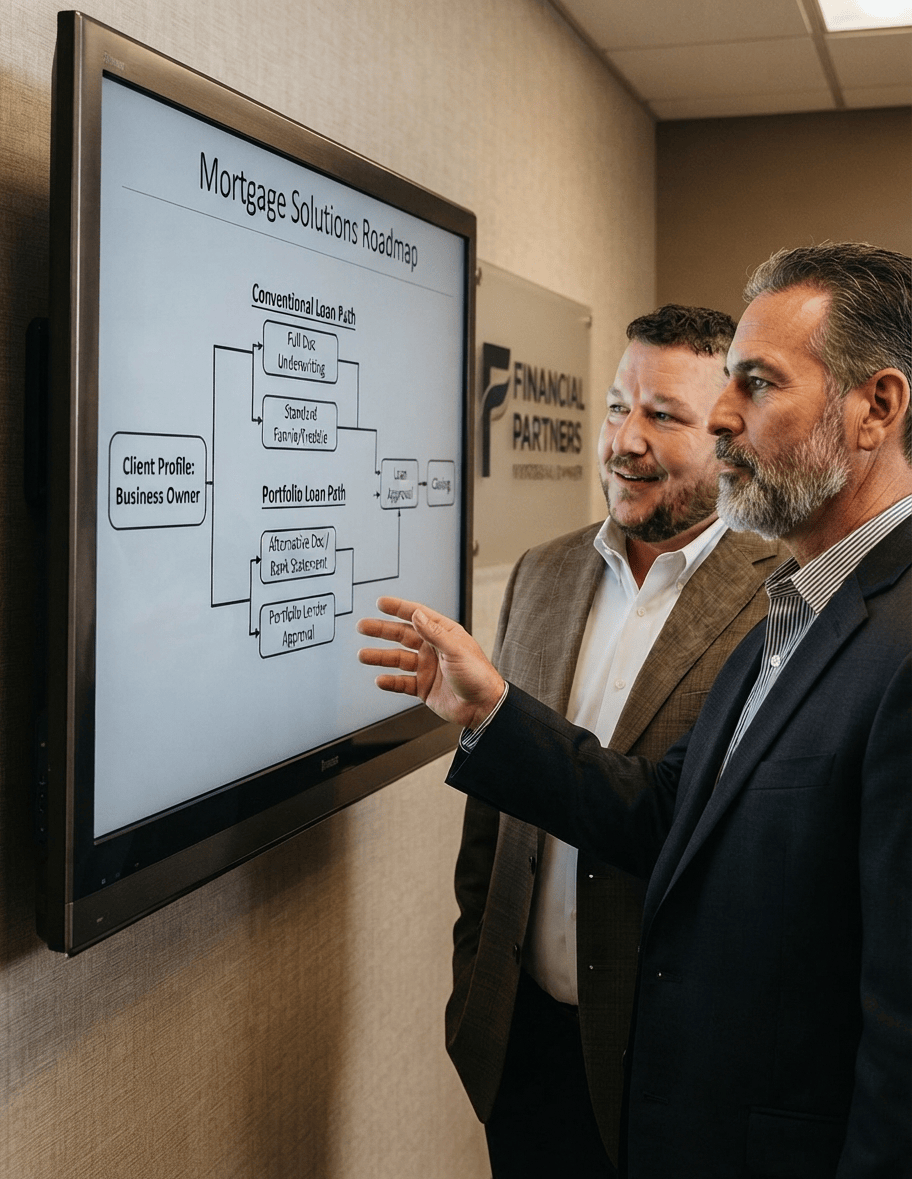
No two financial situations are the same. Before presenting any loan products, our brokers conduct a comprehensive needs analysis. We listen to your unique goals—such as long-term plans

Market Trend
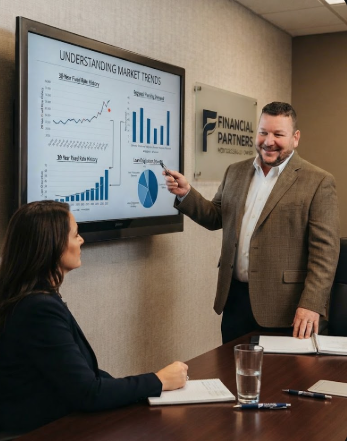
Knowledge is power in real estate. We provide you with up-to-the-minute market insights, explaining current interest rate trends, economic factors affecting the housing market, and how different rate structures (fixed vs. adjustable) will impact your payments over time.

Closing Support
The mortgage process involves significant documentation. We simplify this by utilizing secure digital tools and providing clear, itemized checklists for all required documents. We guide you through every form, manage the underwriting process,
Ready to Secure Your Future?
Get in touch with Premier Mortgage Solutions today. Whether you are buying your first home or refinancing, our expert brokers are here to guide you every step of the way. Contact us now to schedule your personalized consultation!
FAQs
A pre-qualification is a surface-level estimate based on unverified data. My strategic pre-approval involves a deep dive into your tax returns, credit data, and assets. By running this “stress test” upfront, we identify and clear potential underwriting hurdles before you ever make an offer, giving you the same negotiating power as a cash buyer.
It comes down to a “break-even” analysis. FHA is excellent for lower down payments and flexible credit, but it carries permanent mortgage insurance. Conventional loans often have slightly higher rates for lower credit scores but allow you to cancel your PMI once you reach 20% equity. I provide a side-by-side analytical comparison to show which option costs you less over your expected time in the home.
Yes. While many retail banks strictly require 20% down for high-balance loans, my access to specialized “Non-Conforming” channels allows for 10% or 15% down payment options for qualified borrowers. This is a strategic move for clients who prefer to keep their capital deployed in the market rather than tied up in home equity.
C2P is a “one-time close” process. We secure your lot, your builder’s contract, and your long-term mortgage all at once. You lock in your permanent interest rate before construction begins, protecting you from market spikes. During the build, you only pay interest on the funds actually disbursed to the builder, keeping your monthly carry costs low.
Consistency is the key to a smooth closing. Avoid making large, undocumented deposits into your bank accounts, do not apply for new credit (like a car or furniture), and maintain your current employment status. Even a small change in your financial profile can trigger a re-underwrite, so I recommend consulting with me before making any significant financial moves during the process.